How to Qualify for an FHA Loan in Orange County
Understanding the FHA Loan in Orange County Process
FHA loan in Orange County options are worth exploring if you are dreaming of buying a home in Irvine or the surrounding area. As an experienced mortgage broker in Irvine, Karen Edwards understands that navigating the Southern California housing market can feel overwhelming. Fortunately, an FHA loan offers a fantastic pathway to homeownership, especially for first-time buyers or those with less-than-perfect credit.
FHA loans are insured by the Federal Housing Administration. This government backing gives lenders the confidence to offer more flexible qualification requirements compared to conventional loans. Whether you are looking at a cozy condo in Irvine or a spacious family home elsewhere in Orange County, securing an FHA loan can make your homeownership dreams a reality.
Here are a few key benefits of choosing an FHA loan:
- Lower Down Payments: Qualified buyers can put down as little as 3.5%.
- Flexible Credit Requirements: You do not need a perfect credit score to get approved.
- Favorable Interest Rates: Government backing often results in highly competitive rates.
With over 30 years of experience, Karen Edwards can shop over 120 lenders to find the best FHA loan in Orange County tailored to your unique financial situation.
Key Requirements for FHA Loan Approval in California
Qualifying for an FHA loan in Orange County involves meeting specific criteria set by the Federal Housing Administration. While these loans are known for their flexibility, it is important to know exactly what lenders are looking for when you apply.
1. Credit Score and Down Payment
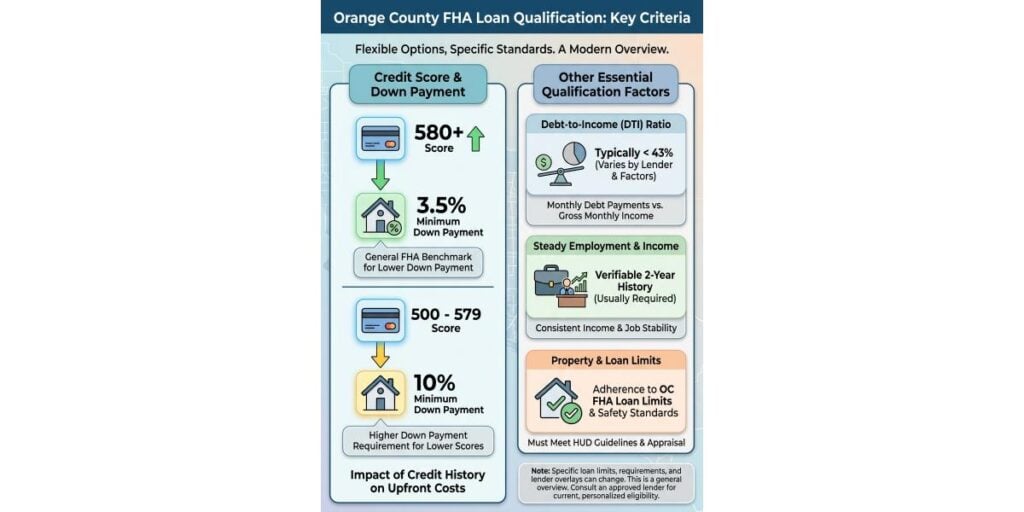
Your credit score directly impacts your minimum down payment requirement. To qualify for the highly sought-after 3.5% down payment, you generally need a credit score of 580 or higher. If your score falls between 500 and 579, you may still qualify but will likely need to provide a 10% down payment. Karen Edwards can review your credit profile and help you understand your best options.
2. Debt-to-Income (DTI) Ratio
Lenders want to ensure you can comfortably afford your monthly mortgage payments. Your DTI ratio compares your gross monthly income to your monthly debt obligations. For an FHA loan, lenders typically look for a DTI ratio of 43% or lower, though exceptions can sometimes be made for borrowers with compensating factors like substantial cash reserves.
3. Property Requirements
The home you wish to purchase must serve as your primary residence. Furthermore, the property must pass an FHA appraisal to ensure it meets strict safety, security, and structural soundness standards. This protects you from buying a home that requires immediate, costly repairs.
4. FHA Loan Limits in Orange County
Because Orange County is considered a high-cost area, the FHA loan limits are significantly higher here than in many other parts of the country. This allows buyers to purchase homes that reflect the local real estate market while still taking advantage of FHA benefits.
